Vendor Reconciliation: What It Is and Why it Matters.

Vendor Reconciliation: What It Is and Why it Matters.

In finance and accounting, reconciliation is the process that keeps financial records accurate, complete, and reliable. Among its many forms, vendor reconciliation plays a vital role in ensuring that an organization’s accounts payable records match those of its suppliers.

Imagine a vendor following up on an invoice they believe is still unpaid. Your ERP shows the payment was made months ago. The vendor shares a statement containing debit notes, credit notes, and other adjustments that don’t exist in your ledger. What initially appeared to be a simple query quickly becomes a time-consuming investigation involving multiple teams and supporting documents.

This is exactly why vendor reconciliation has become a critical finance process. As businesses process thousands of invoices, payments, credit notes, and adjustments every month, differences between vendor statements and internal books become inevitable. Without a structured reconciliation process, these discrepancies can remain undetected for months, resulting in supplier disputes, delayed payments, inaccurate financial reporting, duplicate payments, and unnecessary financial risk. Despite its importance, vendor reconciliation remains one of the most under-automated processes within the accounts payable function.

What Is Vendor Reconciliation?

Vendor ledger reconciliation is the process of matching vendor statements / vendor ledgers  with internal records to ensure that all transactions are accurately recorded and outstanding balances are correctly reflected in both sets of books.  When performed regularly, vendor reconciliation helps organizations detect errors, prevent duplicate payments, recover missing credits, and maintain accurate financial records.

Vendor Reconciliation vs Accounts Payable Reconciliation

These terms are often confused but serve different purposes.

AreaVendor ReconciliationAccounts Payable (AP) Reconciliation
ComparisonVendor Statement vs Internal LedgerAP Subledger vs General Ledger
ObjectiveValidate balances with suppliers / vendorsValidate accounting records
ParticipantsVendor, Procurement, AP TeamFinance Team
FocusTransaction AccuracyFinancial Statement Accuracy
OutcomeSupplier AgreementLedger Integrity

Accounts Payable reconciliation confirms that internal books are correct. Vendor reconciliation confirms that both parties agree. Both controls are essential. Because both controls work together, many finance teams manage customer and vendor reconciliation as a single, streamlined process.

Why Vendor Reconciliation Matters ? 

Vendor reconciliation is not merely an accounting exercise.
It directly impacts:

  • Financial reporting
  • Working capital
  • Internal Control & Compliance
  • Cash flow
  • Vendor relationships
  • Audit readiness

Let’s examine the business impact. 

1. Improves Financial Reporting Accuracy

Unreconciled vendor balances can result in:

  • Understated liabilities 
  • Overstated liabilities
  • Incorrect accruals
  • Misstated expenses

This directly impacts management reporting and statutory financial statements.

2. Recovers Unclaimed Vendor Credits

Many organisations lose money because vendor credit notes are never recorded.
Common examples include:

  • Purchase returns
  • Rate differences
  • Damaged goods
  • Commercial settlements
  • Annual rebates

Without reconciliation, these credits often remain undiscovered.

3. Strengthens Internal Controls

Vendor reconciliation serves as a powerful detective control against:

  • Duplicate payments
  • Unauthorized adjustments
  • Vendor fraud
  • Incorrect postings
  • Process failures

4. Prevents Duplicate Payments

Duplicate payments remain one of the most common sources of financial leakage. Causes include:

  • Duplicate invoice submission
  • Manual processing errors
  • Multiple invoice formats
  • ERP integration issues

Regular reconciliation helps identify duplicate payments before they become permanent losses.

For a deeper look, see our guide on how vendor reconciliation prevents duplicate payments.

5. Improves Vendor Relationships

Suppliers value customers who maintain accurate records and resolve disputes promptly.

Benefits includes:

  • Faster dispute resolutions
  • Improved supplier confidence
  • Better commercial negotiations  
  • Early payment discounts  
  • Extended credit periods

Why Vendor Reconciliation Fails: Common Challenges Faced by Finance Teams ?

Despite being a critical financial control, vendor reconciliation remains one of the most time-consuming and error-prone activities within the accounts payable function. As organizations grow, transaction volumes increase, data becomes fragmented across multiple systems, and manual processes struggle to keep pace.

Below are the most common reasons why vendor reconciliation fails.

1. High Transaction Volumes

Large organizations process thousands of invoices, payments, debit notes, and credit notes every month. Reconciling these transactions manually within the monthly / quarterly close timeline is often unrealistic. As volumes grow, finance teams spend more time matching records than investigating genuine exceptions.

2. Data Spread Across Multiple ERP Systems and Formats

Vendor statements rarely arrive in a standard format. They may be generated from SAP, Oracle, Microsoft Dynamics, Tally, Zoho, Navision, or other ERP systems, while your organization’s ledger resides in a different ERP altogether.

On top of that, vendors share statements in Excel, PDF, scanned images, or even email text. Before reconciliation can begin, finance teams often spend hours cleaning, standardizing, and mapping data received from vendors.

3. Low Vendor Response Rates

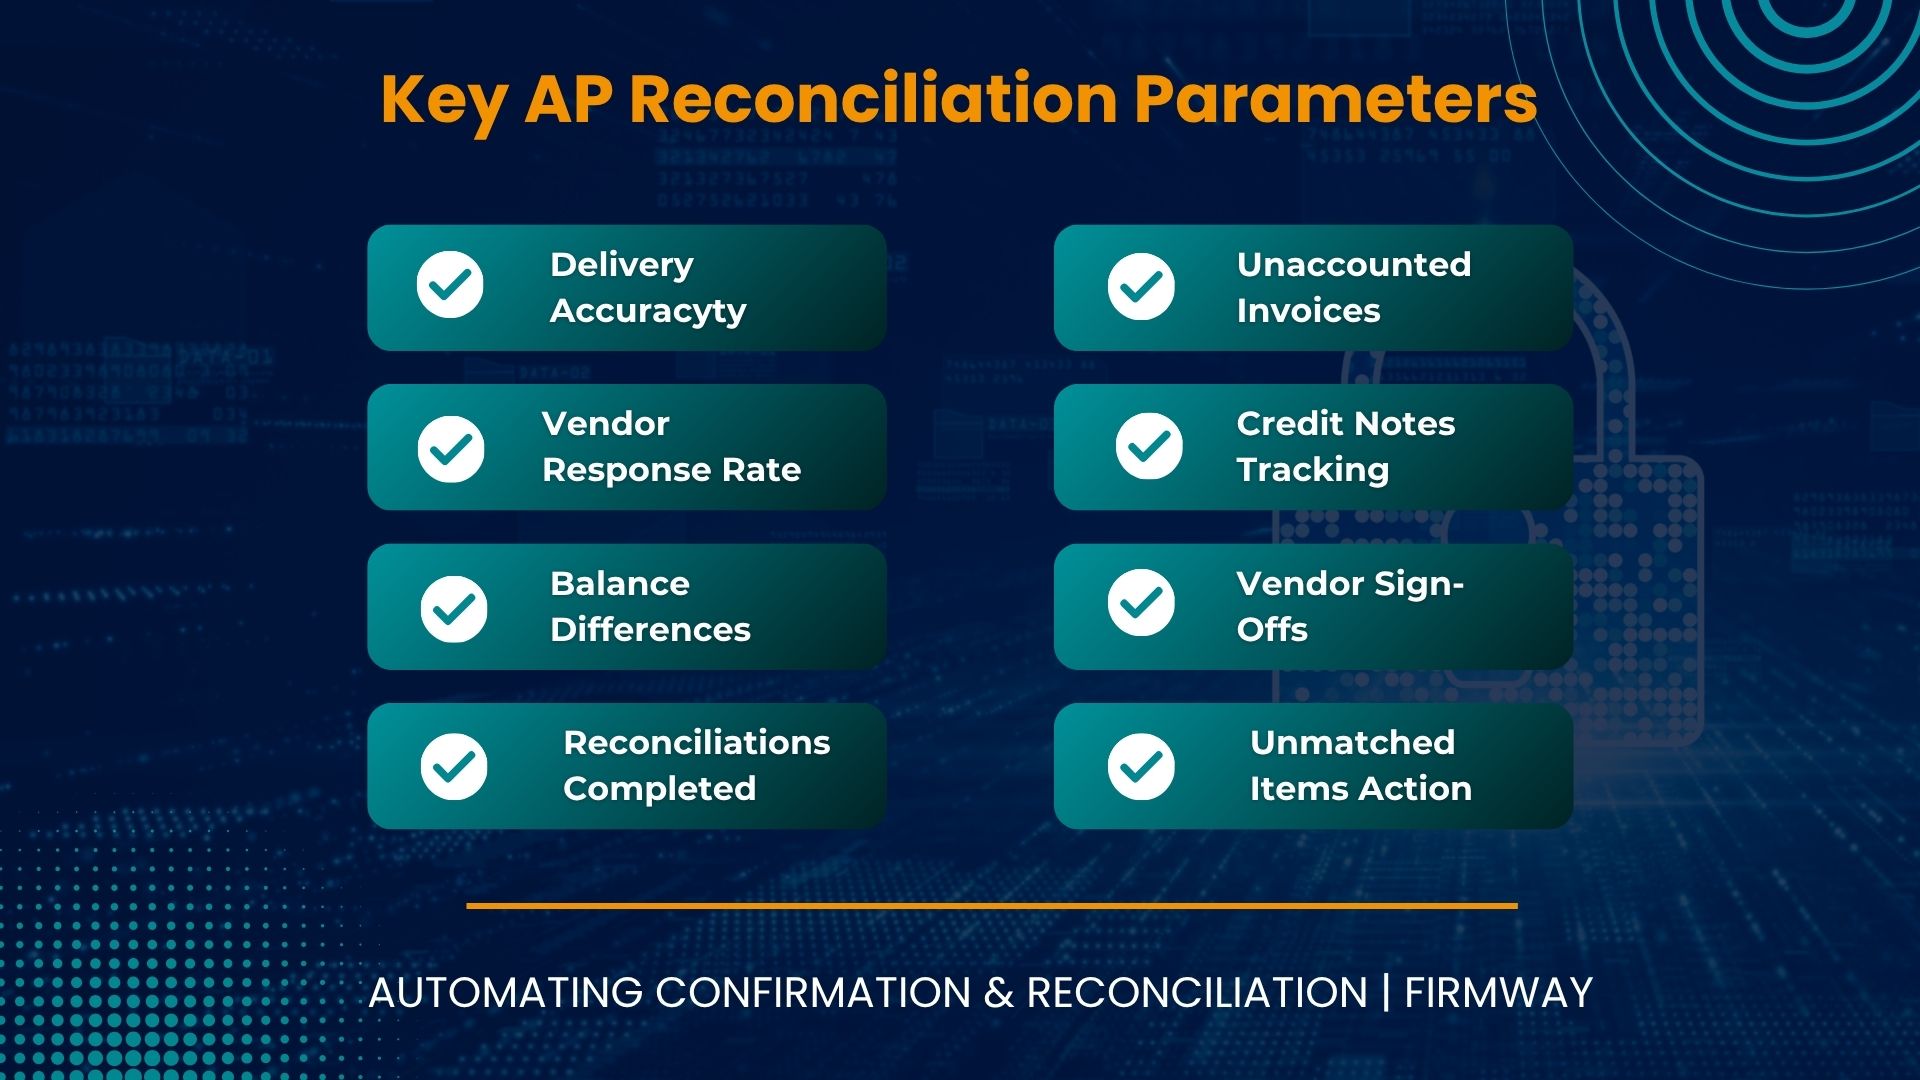
Successful reconciliation depends on receiving timely and accurate vendor statements. However, many organizations receive statements from 10-30% of their vendors. Non Response, delayed responses, incomplete statements, and inconsistent follow-ups prolong the reconciliation cycle and leave balances unresolved.

4. Data Inconsistencies and Missing References

Even when both the organization and the vendor record the same transaction, differences in invoice numbers, payment references, debit note references, credit note references, or amounts (such as those arising from TDS deductions) can prevent transactions from matching automatically. As a result, reconciliation teams spend significant time manually identifying, validating, and resolving these exceptions instead of focusing on genuine discrepancies.

5. Process Dependency and Manual Effort

In many organizations, vendor reconciliation depends heavily on individual team members and spreadsheet-based processes. Knowledge remains with a few experienced employees, making the process difficult to scale, standardize, or audit. This dependency also increases the risk of errors when team members are unavailable or workloads increase.

How Firmway Automates Vendor Reconciliation

Manual vendor reconciliation involves much more than matching transactions. Finance teams spend considerable time requesting vendor statements, following up with vendors, preparing ledger data, reconciling transactions, investigating exceptions, and managing reviews and approvals. As transaction volumes increase, these manual activities slow down the financial close process and increase the risk of errors.

Firmway automates the entire vendor reconciliation lifecycle. From seamlessly integrating with your ERP and collecting vendor statements through automated email and SMS requests, to AI-powered ledger reading, intelligent transaction matching, exception management, workflow approvals, and digital sign-offs, every stage of the reconciliation process is streamlined within a single platform.

Unlike traditional reconciliation tools that rely on exact data matches, Firmway intelligently identifies matching transactions even when there are differences in invoice numbers, payment references, debit or credit note references, or TDS-related amount variations. The platform also provides real-time dashboards to track vendor responses, reconciliation progress, pending actions, and overall process completion, giving finance teams complete visibility throughout the reconciliation lifecycle.

The result is a faster, more accurate, and fully auditable reconciliation process. Instead of spending valuable time collecting statements, preparing data, and manually matching transactions, finance teams can focus on reviewing genuine exceptions, strengthening vendor relationships, and accelerating the month-end close.

Ready to modernize your vendor reconciliation process? Schedule a personalized demo to see how Firmway helps organizations automate reconciliation from statement collection to final sign-off. See how Firmway can streamline your vendor reconciliation
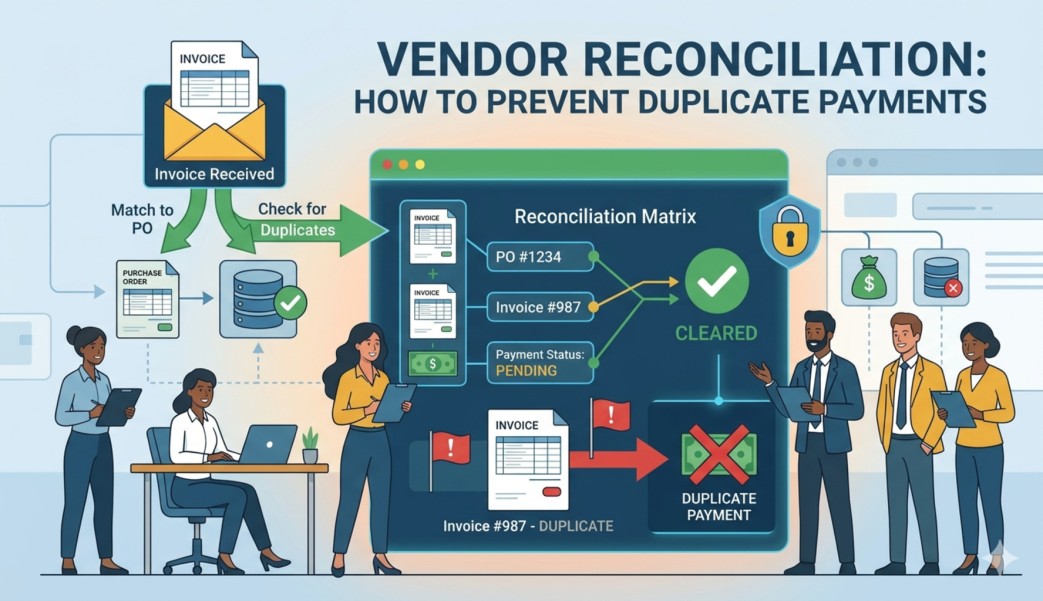
Duplicate Payment Prevention Using Vendor Reconciliation

Duplicate Payment Prevention with Vendor Reconciliation

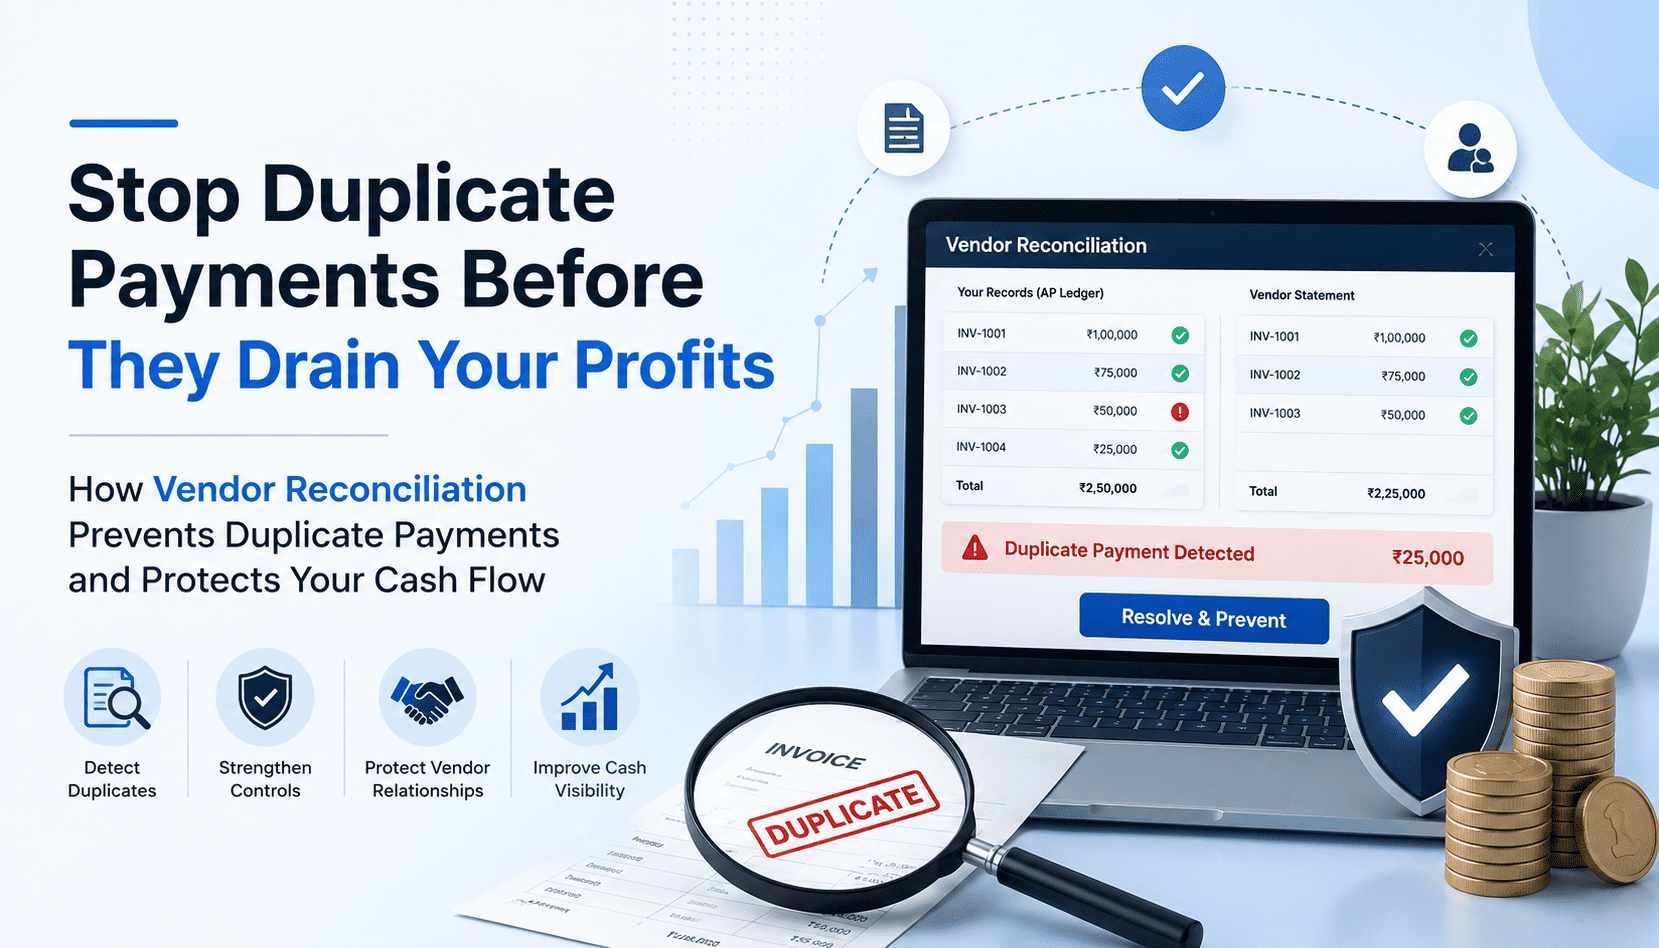
Duplicate Payment Prevention is one of the biggest priorities for modern finance teams. Vendor Reconciliation plays a critical role in preventing duplicate payments before they impact cash flow. Without a solid Vendor Reconciliation process, duplicate payments quietly drain your budget, damage supplier relationships, and create serious compliance headaches. In this guide, you’ll learn exactly how Vendor Reconciliation works, why duplicate payments happen, and the practical steps your team can take for Duplicate Payment Prevention.

The Hidden Cost of Skipping Vendor Reconciliation :

Most finance leaders believe their accounts payable process is airtight. Internal controls are in place. The ERP is configured. The team is experienced. Duplicate payments? “That doesn’t happen here.”

But it does — and more often than most organizations realize.

According to the Institute of Finance and Management (IOFM), 0.1% to 0.5% of all B2B payments are duplicates. For a company processing ₹100 crore in vendor payments annually, that translates to ₹10 to ₹50 lakhs paid out twice — often sitting silently in a vendor’s books, never voluntarily returned.

Vendor reconciliation is the single most effective control to catch these leakages before they compound. Yet, most teams treat it as a back-office arithmetic exercise rather than the cash-protection mechanism it truly is.

Why Duplicate Payments Still Happen Despite Strong Controls

Finance teams often resist the idea that duplicates could be slipping through. Here are the real-world reasons they do, with examples that will feel familiar.

  • Invoice Number Formatting Inconsistencies

This is perhaps the most common and least visible cause. A vendor submits invoice 2300001. Your team books it correctly. The same invoice arrives again this time with the vendor’s reference formatted as 0001 (as printed on a physical copy or retyped by a different person). The system does not flag it as a duplicate because the invoice numbers do not match exactly.

Result: both entries are processed and paid.

  • Paper and Email Channels Running in Parallel

Many vendors send invoices both by email and by post. If your AP team processes email invoices and the physical copy lands with a different person, the same liability gets recorded twice often in different periods or under slightly different vendor names.

  • Manual Data Entry Errors

A ₹1,23,456 invoice keyed as ₹12,34,56 gets rejected during validation. The team re-enters it  correctly this time  but the original, erroneous entry was already processed for payment before the error was caught. Two payments exit.

  • Vendor Name Variations in the Master Data

“Tata Consultancy Services,” “TCS,” and “TCS Ltd.” may all exist in your vendor master as separate records. Payments against the same underlying vendor and the same invoice can go through on different records without triggering a duplicate alert.

  • Credit Note Not Applied Before Payment

A vendor issues a credit note for ₹25,000 against a disputed delivery. The credit is recorded in your books, but when the next invoice arrives, the AP team processes the full amount without netting the credit. You have overpaid by ₹25,000 not a classic duplicate, but equally a cash leakage that reconciliation is designed to catch.

  • System Migrations and Cut-Overs

During an ERP upgrade or entity merger, historical transactions are migrated. Some invoices already paid in the old system get flagged as “open” in the new one and are processed again in the first payment run.

Duplicate Payment Prevention in Accounts PayableHow Vendor Reconciliation Supports Duplicate Payment Prevention
Vendor reconciliation specifically, matching your AP ledger against the vendor’s statement creates an independent verification layer that your internal controls alone cannot provide.

  • On invoice number mismatches:

When you reconcile against the vendor’s statement, the same transaction appears once on their side. So if your books show two payments for what the vendor records as one invoice, the mismatch becomes immediately visible regardless of how differently the invoice number was formatted at the time of booking.

  • On parallel channel duplicates:

A vendor’s statement reflects what they’ve billed you, not how many times your team received it. As a result, reconciliation collapses both entries into a single verifiable transaction.

  • On vendor master fragmentation:

Reconciliation happens vendor by vendor. Even if “TCS” and “TCS Ltd.” exist as separate master records, the exercise forces your team to engage with the actual vendor and consolidate the full picture of your liability to them.

  • On unapplied credit notes:

The vendor’s statement will show the credit note as an offset. Therefore, if your ledger doesn’t reflect it, the gap surfaces during reconciliation before the next payment run.

  • On post-migration open items:

A reconciliation performed soon after go-live will immediately expose transactions the vendor considers closed but your new system still shows as payable.

In each case, the logic is the same: your internal records and the vendor’s records cannot both be right. Reconciliation forces that confrontation and the earlier it happens, the less cash has already left your account.

Conclusion: Duplicate Payment Prevention Requires Smarter Vendor Reconciliation

Duplicate Payment Prevention isn’t just about avoiding accounting errors—it’s about protecting your cash flow, vendor relationships, and financial credibility. Moreover, when done consistently, vendor reconciliation is your most reliable line of defense.

But manual reconciliation is time-consuming and error-prone. And as your vendor base grows, the cracks only widen. So the question is no longer whether you need a robust vendor reconciliation process it’s how quickly you can put one in place.

That’s where Firmway comes in. Firmway’s automated vendor reconciliation software detects duplicate payments before they go through, matches invoices and payment records at scale, and gives your finance team real-time visibility into every vendor account without the spreadsheet chaos.

Stop overpaying. Start reconciling smarter.

MSME Vendor Identification

MSME Vendor Verification: Best Practices for Vendor Database

In the present business world, having accurate and updated vendor data isn’t just about good record keeping; it’s about smart compliance and stronger control. A critical aspect of this is MSME vendor verification, which ensures you correctly identify your vendor’s MSME (Micro, Small and Medium Enterprise) status and stay compliant with regulatory requirements.

Let’s look at why it matters, and the best practices every finance or procurement team should follow to keep their MSME vendor database accurate and reliable.

Why MSME Vendor Verification Is Necessary for Vendor Compliance?

MSME vendor verification allow you to:
1. Identify which vendors are entitled to payment protection and/or priorities under the MSME Act.
2. Prevent incurring interest penalties, wherever applicable, on delayed payment to MSMEs and safeguarding yourself from the 43B(h) disallowance.
3. Properly classify vendors for reporting with ROC, audits, and internal controls.

In short, identifying MSMEs brings clarity, compliance and accountability to your vendor process. Outlined below are key practices for building and sustaining an accurate, compliant, and up-to-date MSME vendor database.

MSME Vendor Verification1. On-boarding checklist : A Corporate KYCs
When on-boarding a vendor it is best practice to collect all important information PAN, GST, bank account information and MSME status so that you can ensure your database is clean and compliant from the very first day.

2. The Critical Need of Taking Declaration from Vendors Every Year:

MSME registration is not mandatory from day one of commencement of business, it can be taken at a will of the Vendor if required criteria are being met.

When a vendor initially onboard with your organisation, they may not be categorized or classified as an MSME, and then later they still have an option to get registered if all the criterias are being met. So taking their declaration every year ensures that you are working from the latest updated MSME information and protecting yourself from compliance gaps based on outdated vendor status.

3. API Verification Every Year to identify the Classification:

The three categorizations in MSME- Micro, Small, Medium come with varied compliance requirements in relation to payment, disclosure, reporting and benefits. So,recognizing these distinctions is not merely descriptive but operationally significant.

Govt, suo-moto, keeps updating the classification of registered MSME Vendors every financial year during the month of April-May. Accordingly, precise classification becomes essential, as compliance actions are considered valid only when aligned with the vendor’s verified UDYAM-registered classification.

Therefore, it is recommended to verify the updated classification every year through Udyam APIs.

In conclusion, a reliable MSME vendor database is built on accuracy, periodic validation, and structured automation from capturing complete information at onboarding, to annual verification of MSME declarations, and validating classifications through Udyam details. These practices create transparency, control, and a single source of information across procurement, accounting, and compliance, while reducing the risk of errors, penalties, and audit gaps. This is where Firmway plays a critical role by enabling end-to-end MSME verification and classification through Udyam API integration, helping organisations like Asian Paints, IPCA, Nykaa, Ameya Logistics,ESL Steel, Fiat, Infosys, Gharda Chemicals, Lupin, Runval, Tata Realty, Toyota, Blue Star, institutionalise compliance at scale.

MSME Vendor Onboarding in India

MSME Vendor Onboarding in India: Here’s Complete Legal Guide

Legal and Compliance Aspects of MSME Vendor Onboarding in India

Micro, Small, and Medium Enterprises (MSMEs) play a pivotal role in India’s economic growth, contributing significantly to employment generation and industrial output. As the Indian government continues to promote the MSME sector, evidenced by initiatives such as increasing limits for MSME/Udyam Registration, Compulsory Registration with TReDS for companies with turnover above INR 250 crore and other such measures, understanding the nuances of MSME vendor onboarding is crucial for businesses seeking to engage with these enterprises effectively.

Legal Necessities for Identifying MSME Vendors During MSME Vendor Onboarding:

1. Disallowance under Income Tax Act: One of the key aspects to consider in MSME vendor onboarding is the disallowance :

a) under Section 43B(h) of the Income Tax Act, 1961 – Disallowance in case of non-timely payment
b) Disallowance for interest paid to MSME’s for delayed payment of their dues.

2. Reporting to Registrar of Companies:

Companies engaging with MSME vendors need to report the particulars of their transactions with MSMEs for statutory compliance. This reporting requirement, mandated under the Companies (Accounts) Rules 2014, is crucial for transparency and regulatory adherence. Failing to report such transactions can lead to legal complications, making it essential for businesses to fulfill this obligation promptly.

The above necessities and the urgency Government is demonstrating to support MSME emphasizes that companies must identify such MSME Vendors from the very beginning of business relationship with them.

MSME Vendor OnboardingMSME Vendor Onboarding: Details to Collect for Vendor MSME Status:
Udyam Certificate: If possible, companies shall prefer the Udyam certificate with updated details such as latest classification, current activity codes etc. for a current financial year in which the vendor is getting onboarded.

Latest Classification: Classification into a Micro, Small or Medium Category, if the same is not available with the vendor, then companies shall run real-time APIs, provided by Government, to identify the same as many compliances are not applicable in case of Medium Category.

Nature of activities: Nature of activities determines which compliances are applicable for a particular MSME vendor. If the nature of the activities for which vendor is registered under MSME Act and the activities for which it is engaging with a company are different then a company shall request a vendor to modify its Udyam Certificate.

Vendor Declaration: Company shall collect from the vendor, a declaration stating that any change in its MSME classification or status shall be communicated to the company through a specified mode only or this declaration can be a part of the contract or Purchase Order (PO) itself.

Conditions in Purchase Order: PO shall specify that any question asked by company on MSME status and classification must be responded to, failing which company shall have a right to assume the Vendor is Non-MSME or continue with the classification and status available with it.

Conclusion :-

MSME vendor onboarding in India involves meticulous attention to legal and regulatory requirements and documentation. The documentation list provided above will help in supporting your position or reason for non-compliance in case of any queries or legal disputes. By adhering to these guidelines, businesses can not only comply with the law but also foster sustainable and mutually beneficial relationships with MSME vendors, contributing to the growth and development of the Indian economy.